Cashback and daily bonuses, side by side
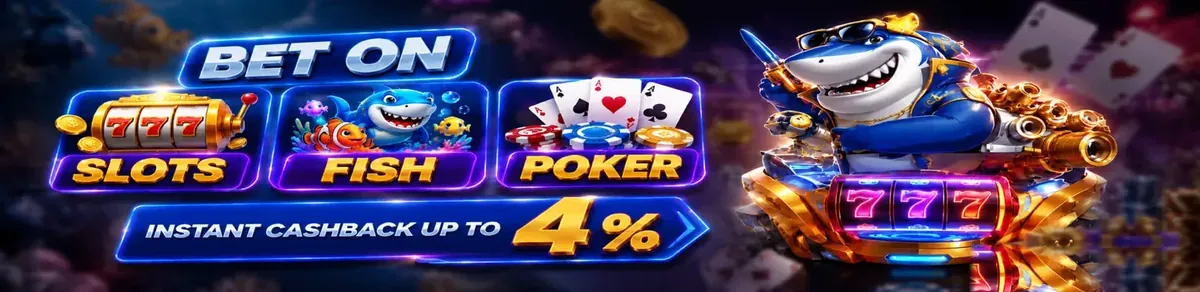
Instant cashback programs provide consumers with a direct return on their qualifying expenditures. On the apex88 platform, promotional displays display specific rebate rates alongside daily top-up incentives.
Readers can review every reward on the current banners to assess how these promotional items are positioned. A proper evaluation requires examining the exact percentage figures published on marketing materials.
Cashback percentages determine the proportion of funds returned following specific gaming activities. The promotional banners display different rates depending on the category of play. Comparing these printed rates against standard commercial models clarifies how promotional liquidity functions. Analytical readers inspect the exact terms associated with each headline figure.
Deposit bonuses offer another mechanism for adjusting balance totals. These incentives apply an additional percentage to incoming funds on a recurring schedule. Both structures aim to alter the cost balance for the participant. Evaluating both mechanisms side by side clarifies their financial mechanics.
Percentage banners
Instant cashback calculations depend directly on the rates shown on promotional graphics. The instant cashback banner prints INSTANT CASHBACK UP TO 4% for bets on slots, fish and poker. Readers should note that this specific graphic does not print a turnover requirement, a minimum deposit amount or an expiry date. The stated 4% figure represents the maximum ceiling published on the promotional material.
Daily deposit bonuses operate under different percentage caps across game categories. The daily deposit bonus banner prints DAILY 8% DEPOSIT BONUS without additional qualifying criteria on its face. Furthermore, the live casino daily deposit banner prints DAILY 10% DEPOSIT BONUS as a separate promotion. None of these promotional materials display wagering requirements, required deposit thresholds or explicit validity periods.
Banner representations must be read strictly according to their visible numbers. When a graphic displays 8% or 10%, it states a clear nominal proportion for that specific category. The banner prints no condition regarding play-through multiples or settlement timelines. Comparing these numbers helps readers understand the published parameters before making decisions.
Financial structure
Cashback reward structures function by returning a designated fraction of total expenditure back to the spender. A cashback reward program refunds consumers a small percentage of the total amount spent on qualifying financial transactions. A rebate is a partial refund given to a consumer after a purchase has taken place. This retrospective adjustment lowers the effective net cost of the completed activity.
Operator balance sheets account for promotional costs as deductions from total turnover. Net revenue for commercial operators accounts for gross receipts minus direct transaction costs, taxes, and promotional rebates. Rebate allocations therefore represent direct offsets against incoming merchant receipts. These reductions alter the final margin retained by the commercial firm.
Differential pricing strategies frequently govern promotional distribution across different market segments. Price discrimination involves charging distinct customer segments different prices or refund rates for essentially identical goods or services. Liquidity refers to the efficiency with which an asset can be converted into ready cash without impacting market value. Promotional funds with immediate conversion access display higher liquidity than funds tied to pending settlement intervals.
Mental accounting
Cognitive frameworks influence how individuals perceive promotional refunds and gaming balances. Mental accounting describes how individuals categorize, evaluate, and track financial activities across separate cognitive compartments. The house money effect leads individuals to take higher financial risks when playing with money perceived as house earnings. Money returned through a rebate is frequently placed in a separate cognitive category from primary deposited capital.
Risk perception determines the subjective evaluation of potential negative outcomes. Risk perception refers to subjective judgments people make about the severity and probability of encountering adverse negative consequences. Financial literacy equips consumers with the conceptual knowledge necessary to make informed decisions regarding personal money management. Cultivating this literacy enables individuals to separate promotional marketing figures from actual expected returns.
Behavioral economics shows that human beings evaluate monetary gains and losses asymmetrically. Prospect theory demonstrates that value functions are steeper for losses than for gains of an equivalent monetary size. Receiving an unexpected rebate can mitigate the perceived psychological impact of an expenditure. Maintaining clear cognitive accounts assists participants in setting limits across all activities.
Settlement intervals
Financial distribution relies on formal settlement architecture and operational rules. A payment system comprises established instruments, banking procedures, and fund transfer mechanisms facilitating financial circulation. Electronic funds transfer enables electronic exchange of money from 1 bank account directly to another without paper documents. This electronic infrastructure forms the foundation for digital cash movement across modern platforms.
Transfer protocols vary significantly in their processing speed and verification routines. Real-time gross settlement systems process individual monetary transfers continuously and immediately on a transaction by transaction basis. Commercial services depend on these continuous flows to clear outgoing payments without batch delays. However, this analytical guide cannot confirm which schemes the operator accepts.
Regulatory compliance mandates strict identity checks and transactional auditing for all monetary processors. Anti-money laundering regulations require financial intermediaries to monitor customer transactions and submit suspicious activity reports. Know your customer standards compel regulated entities to verify user identity before authorizing financial withdrawal transactions. These supervisory steps ensure that fund distributions follow established legal and administrative frameworks.
Reference questions: cashback and daily bonuses
What does the instant cashback banner display?
The instant cashback banner prints INSTANT CASHBACK UP TO 4% for bets on slots, fish and poker. It prints no turnover, minimum deposit or expiry date on the graphic.
How do the published daily deposit bonus percentages differ?
The standard daily deposit graphic prints DAILY 8% DEPOSIT BONUS, while the live casino version prints DAILY 10% DEPOSIT BONUS. Neither graphic shows a turnover or minimum deposit requirement.
How does a rebate differ from an upfront deposit bonus?
A rebate serves as a partial return granted retrospectively following completed transactions. An upfront deposit bonus adds a specified promotional percentage directly at the point of incoming funding.
Why do withdrawal procedures require identity verification?
Financial processors must comply with know your customer and anti-money laundering standards. These rules mandate identity confirmation and transaction auditing before funds are cleared for withdrawal.